#OutToLunch Ongoing URA changes should address SME challenges


By Denis Jjuuko

Over the weekend, several senior managers at the Uganda Revenue Authority (URA) tendered in their resignations ostensibly to pursue other careers. Social media as is usually the case went overboard with some people claiming it was a purge that the officers didn’t choose to resign rather forced to do so.

URA issued a statement saying the board made recommendations concerning the “reorganization and management” but “some senior officials chose to resign and the board accepted their resignation.” There is nothing new in mass resignations in organisations following an appointment of a new boss.

However, what concerned me was the statement, which talked about “reorganization and management of URA” though my concern isn’t merely in the personnel, those can always be replaced. The way URA works is what needs to change and I hope the “reorganization and management” will consider small and medium enterprises (SMEs).
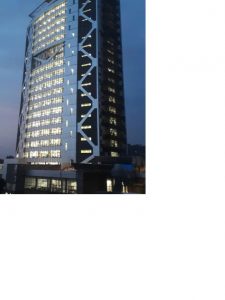
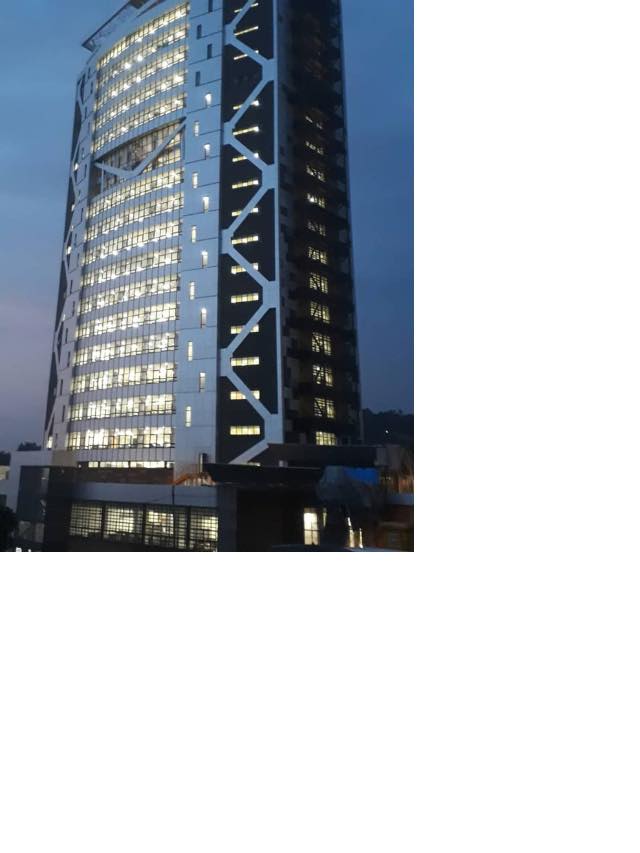
URA Towers

There is a need to change or push to change the many taxes that end up strangling small businesses. The income tax rate is at 30%, excise duty at 15%, withholding tax at 6% and VAT at 18%. All these taxes may be fine for large organisations, but for small companies, they are a death sentence. So imagine a company that gets a Shs100m contract, runs to the bank to get a loan to execute the assignment and the loan is granted at 24%. If they pay all those taxes and the interest fee, what do they remain with?

But before the company even gets a contract, it must submit a tax clearance certificate (TCC). Some years ago, URA people sat in a boardroom and came up with an ingenious idea —TCC must be issued per a bid. So if you are bidding for work in Company A today, you apply for a TCC that goes to Company A and if tomorrow you need to make another bid to Company B, you apply for another TCC. Never mind that you just got a TCC a day before. The funny thing is that today URA can issue you a TCC and tomorrow they can reject to give you one. I don’t know what makes URA issue a TCC today and refuse to issue another tomorrow.

This process of applying a TCC per bid is another cost for SMEs because many rely on external consultants to process these certificates for them. Why doesn’t URA issue a TCC for say six months or one year? If they fear that SMEs will forge them, they can a create verification system. If people can quickly verify in whose name is a vehicle registered at URA, why can’t they verify whether a TCC is genuine or not?

Taxes like VAT should also be reformed where SMEs don’t have to pay URA once an invoice is issued rather when they have been paid. I know there is an option for this but its administration is even more complicated than paying URA before a company is paid because you must have paid all your VAT before you allowed this option. Where does an SME get the money to pay taxes for money it is not sure will be paid on top of servicing loans at crazy rates?

URA sometime back introduced a very good system where some types of businesses are charged a set rate as income tax. They call it a presumptive tax. Businesses like salons pay this rate instead of self-assessments. The figure payable is set regardless of the profit made. I think this is a very good way of taxing SMEs. However, they left out many businesses that could pay more taxes if they were asked to pay a fixed rate. Self-assessments are cumbersome to both the small taxpayers and URA. The URA needs many staff to look at documents before they accept that the self-assessment is correct. Many times, URA refuses self-assessments and institutes charges that are way above what an SME made in a year. That involves a lot of back and forth before the tax is paid if ever paid. There is a need to widen businesses that pay a presumptive tax rate but also consider the size of business. The other alternative is to have an income limit where, for example, if the business earns less than a certain amount a year is allowed to pay a presumptive tax than going through the cumbersome processes of self-assessment. This will reduce the number of companies filing zero profits and therefore paying nothing in income tax.

Also, URA needs to handle SMEs differently. For example, the assessment forms for Withholding Tax exemptions shouldn’t be the same for all taxpayers. A simple form for a small business is sufficient whereas, for the largest taxpayers, they can have a form that fits their size.

As URA was issuing statements about its staff resignations, MTN was issuing another regarding a tax case involving Shs326 billion which the telecom giant questioned in court. The assessment came to Shs24 billion but MTN further appealed to the Tax Appeals Tribunal. To cut the long story short, MTN got an interim order against the enforcement of URA notices. MTN as a large company can afford silver-tongued lawyers and appeal even for 20 years but SMEs can’t. A mere lack of a TCC is a disqualification from a potential contract. Excessive assessments from URA simply lead to heart attacks for the owners and closure of the business. URA enforcement officers also love small companies — they quickly attach bank accounts, put padlocks on the premises and such other things. For the big boys, they simply sit on the table or go to court.

Changes at URA, therefore, shouldn’t stop at just personnel but the way tax administration is carried out especially for SMEs because they are the majority and employ more people collectively. Customer care is critical if URA is to achieve its tax targets and SMEs can play a critical role if URA invested time and resources to understand them and address their challenges.

The writer is a communication and visibility consultant. djjuuko@gmail.com
Related

Out to Lunch

#OutToLunch: Should parents give away their wealth when they are still alive?

By Denis Jjuuko There is a series of videos that has been trending on TikTok and other social media platforms where a son is accusing his biological mother of killing his biological father by denying him treatment abroad and/or sanctioning an operation she knew he wouldn’t survive. The videos have been circulating because the deceased was a prominent businessman and one of the wealthiest people in Uganda. And the son claims wealth was the reason his father “was murdered”. The accusations have caused discussions on social media. Lawyers have recorded podcasts on writing wills and what the law says. Upon listening to these stories, some people said they had started the process of writing wills. Anyway, fights over property aren’t new and they will never end. Not long ago, somebody else took his father to court accusing him of being too sick to run his business empire and therefore should be appointed his successor. The father who was taken to court is also one of the wealthiest people in the country. It is perhaps the first case in Uganda where one demands for their inheritance when the parent is still alive since the famous prodigal son Bible story. Many families face this problem including those without wealth to write home about. First born sons are known to throw tantrums when not named heirs of their fathers. Some go at length of forging wills so that they are named heirs or disputing wills of their fathers. Others where they are not elected heirs in case a will didn’t exist cause unbelievable chaos once they lose the election. Others forcibly occupy the properties while many sell off to unsuspecting buyers and refuse to share with their siblings or even surviving parents. If you watch some of the local news on TV, you will see children evicting their mothers or relatives dislodging widows. Given the stories that are today going around, wealthy people must be having sleepless nights thinking about what will happen to their estates once gone. More money more problems, Notorious BIG told us decades ago. In one of those podcasts and X Spaces that have been organised to discuss wills and inheritance, a lawyer from a prominent Kampala law firm urged people to will themselves something. He said when you are writing your will, give yourself 30%. People gasped for breath on hearing that. What would a dead person do with 30%? It didn’t take too long for him to argue that the 30% is what you should be enjoying before you die. He was perhaps aware that there are many people who live miserable lives while preserving everything for the children. The children, if one is lucky, will wait for the parents to die before going for each other’s throats over the property or even sell it off before the deceased is even buried. The unlucky ones are taken to court or accused of killing their spouses. Somebody told me that to forestall these fights, he regularly goes on dates with his children reminding them at every given opportunity that his wealth is his and his wife’s only. That he has taken them to the best schools and therefore they have received already their inheritance. He tells them that his wealth wasn’t bequeathed to him by his parents. He claims they have listened and understood. Maybe they have. But when he isn’t around anymore or in a position where he can’t make decisions, things may turn out different. You see, most people think they have done a great job of raising their children. The children are good at disguising themselves as well. Once the parent is gone or severely incapacitated, the true colors are revealed. This isn’t just in Uganda. The Rupert Murdoch children have been fighting over News Corp (Fox, Sky etc.) for years though they recently agreed to a trust agreement. Their father is still alive but at 95 years old unable to reign them in. What should parents especially the wealthy ones do? Create a trust that manages the properties and distribute the proceeds as instructed but that idea is still new in Uganda. The easiest way could be for wealthy parents to distribute the assets when still alive, transfer full ownership to those being bequeathed. Many people have done that and limited the flow of bad blood once dead or severely incapacitated. The writer is a communication and visibility consultant. djjuuko@gmail.com See less
Read More »
Out to Lunch

#OutToLunch: Are investment clubs ruining your life?

By Denis Jjuuko The internet has led to connectivity we probably never imagined. Previously, you left a job and that was it. Today, if you leave one, most likely somebody will add you to a WhatsApp group of former employees of Company Z. If you don’t leave the job, you belong already to several WhatsApp groups. The schools you attended also have another WhatsApp group. And of course, another for the particular class say Law Class of 2005. If you attended many schools, you are in several of these. The neighbours also have another group. Your ancestral village has another one for its Kampala diaspora. The religion you belong to has several others. The one where you live, and another from your ancestral district or diocese. The gym colleagues have another one. The social clubs you belong to also have others. The list of WhatsApp groups can be endless and sometimes it can be hard to catch up. Some people, perhaps afraid of annoying people if they left, resort to being silent or what Ugandans call akamooli (watching from the sidelines). However, most of these WhatsApp groups have one thing in common — investments or savings. There is perhaps no WhatsApp group where an investment or savings club hasn’t been mooted. Because everyone wants to save and make some ka-money, the idea usually is supported by many members. And indeed some of these investment or saving clubs have blossomed. Some old students or church associations now have billions in assets under management. Many people feel that they shouldn’t be left out and go ahead and sign up to many investment or savings clubs. Each of them expects one to pay a set amount of money every month. Failure to pay can be psychologically torturing. Treasurers are cajoling each one of the members to meet their obligations. Meetings spend half the time devising means to ensure everyone is paying and how to discipline those falling short. I know of somebody who was consistently broke. He was earning a decent monthly salary but he was always stressed and pitiful. I found out that he was belonging to several clubs in Kampala and his ancestral village. They took a significant part of his pay. He was living a miserable life as he tried to meet his obligations with the several investment clubs he belonged to. Saving and investing is a very good thing but it should be of a certain percentage of one’s earnings. If you save and invest for example 70% of your earnings, you must ensure that you can survive on the remaining 30%. If you are saving 70% of your earnings and then playing dodge ball with your landlord at home, failing to get basics for your family, then it makes no sense. Being super stressed because of saving isn’t probably the right thing to do. The repercussions can be dire. Many people suffering to meet their saving obligations in clubs as largely a result of subscribing to many clubs. The best way is to identify a club or two which meet your aspirations and concentrate on those than being in so many clubs and failing to meet your obligations. It frustrates everyone including yourself. Investment and savings clubs however good they are for people and economies, they are very conservative. In order to protect people’s money, they usually invest in assets that are considered safe but sometimes without even regular returns. People can have money in these clubs but they aren’t taking home anything regularly. If a club invests in land or even unit trusts, they have to wait for a long term for either the land to gain value and sell or for the unit trusts to compound significantly to provide a worthy return to the members. Are you willing to wait for that long? Those that lend money to the members charge very high rates, sometimes as much as 3% per a month. Annually, that is 36%. Just because there isn’t much paperwork, collateral and are swifter than commercial lenders, the interest rates are simply prohibitive given that members are essentially borrowing their own money. Investment and savings clubs if they want members to make money, they need to lend below annual interest rates of banks. Since they do short term lending, they could do 0.5% a month. People who are borrowing this money, they could then be able to make money with what they have borrowed. So as your WhatsApp group proposes yet another investment or savings club, be careful before you sign up and see if it makes sense or the ones you belong to are enough. The writer is a communication and visibility consultant. djjuuko@gmail.com
Read More »
Out to Lunch

#OutToLunch: Practical skills still important even in the AI era

By Denis Jjuuko The new British prime minister (yes, there is a new one) has been ubiquitous trying to sell his vision and probably avoid the missteps of his predecessors. In one of the videos he shared on his social media handles, he is seen at a factory that makes trains. He says, artificial intelligence or AI won’t build them. He said AI can write a contract but it won’t make a train like the factory he was visiting or even fix your leaking roof. Andy Burnham is probably the first political leader of a developed economy to say that on camera. His vision is of seeing technical practical jobs being created alongside digital ones. He also acknowledges the limitations of digital innovation. He called for a reboot of his country’s education system. Desktop jobs may be replaced by AI but the practical ones will still exist. As Andy Burnham was sharing the video, the Uganda Airlines acting Chief Executive, veteran Ethiopian aviation expert Girma Wake was holding a presser at his Nakasero office in Kampala. Wake was once the top guy at Ethiopian Airlines, well known for its efficiency, safety and profitability — an exception on the continent. His video interview, in less than five minutes, was confidence building. He offered his vision, underlying briefly what is required to ensure the crane continues to soar as high as it is expected. I think it is going to be a long journey but it seems basics are now in place. One of the things he mentioned was the cost of employment. When Uganda Airlines was collapsed in 2001, Ugandans who had aviation experience moved on. Young people saw no reason to enroll for aviation courses. Those who wanted to pursue certain careers in aviation largely had to finance their education and training outside the country. That is usually very expensive. Today, Wake told his audience, he relies on foreign staff to operate especially the aircraft on wet leases. He says that is very expensive. He needs Ugandans in those jobs. They are affordable and due to family ties and other reasons are more likely to remain with the airline for the long haul. Aviation employs many people. With Uganda Airlines expecting to receive its delivery of eight aircraft from Boeing in early 2030s, many people who go to aviation schools today will perhaps have gained some experience by that time. A simple google search shows that one B737 aircraft needs 10-15 pilots to operate and many others in other jobs in operations and maintenance. Broadly, it may need as many as 80 people for optimum operations. The national carrier’s executive also talked about reviving the flying school in Soroti. I think that now we have a firm order with Boeing, this is even more urgent. So that by the time the aircraft are delivered, there would be Ugandans to operate and maintain them. And AI will not solely operate and maintain the aircraft. It won’t cook the rolex or katogo Uganda Airlines may want to serve on the flight. Though those with the right AI skills will have a bigger chance of landing a job. But it isn’t just aviation where AI, like the British Premier said, would be limited. We are constructing the Standard Gauge Railway (SGR) and even reviving some meter gauge ones. Are we training people to operate and maintain the line, trains or even build them? Or we will rely on experts once the SGR is built like we are doing with a simple job of managing toll gates on the Entebbe Expressway? We are still very much a small economy that will for a long time depend on the practical physical skills of its people. Skilling in technical practical jobs is still important for the majority of people. The automotive industry is experiencing changes as people move to electric and more advanced vehicles. Do we have repair shops that are competent to repair and maintain them? I see an increment in electric and newer model vehicles on the road every day. The garages or workshops are improving too — moving their operations from under the mango tree to somewhat fancy buildings. But are we training people in the numbers we need to do the job? And if Britain is going back to the basics during this era of AI, what about us? To achieve our US$500b economy goal will depend a lot on many of our young people having the skills they need to find jobs with predictable regular income. The writer is a communication and visibility consultant. djjuuko@gmail.com
Read More »